FCF growth
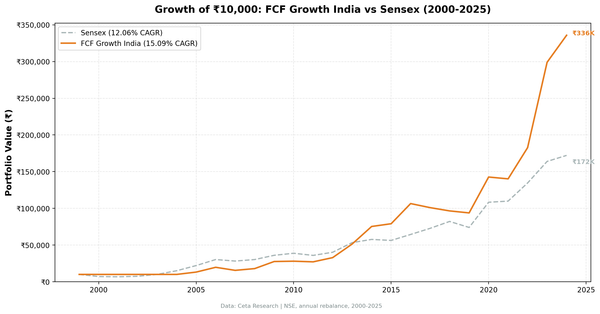
FCF Growth in India: 15.09% CAGR Over 25 Years (NSE Backtest)
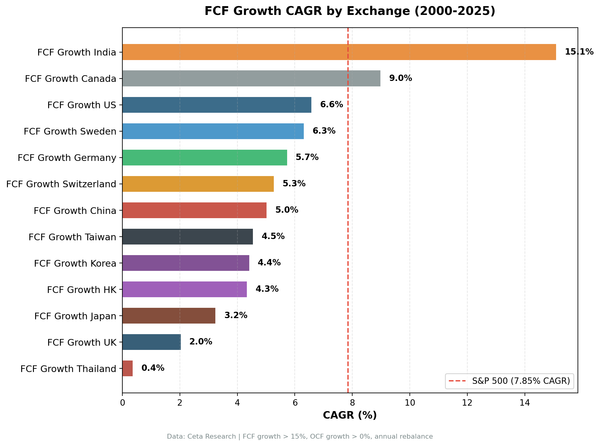
₹10,000 grew to ₹335,761 over 25 years using a free cash flow growth screen on NSE stocks. 15.09% CAGR, +3.03% above the Sensex, and a 36.9% down capture ratio.

FCF growth
₹10,000 grew to ₹335,761 over 25 years using a free cash flow growth screen on NSE stocks. 15.09% CAGR, +3.03% above the Sensex, and a 36.9% down capture ratio.
FCF growth
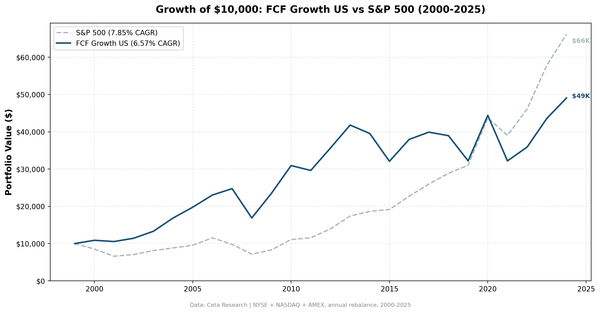
We backtested FCF growth stocks across NYSE, NASDAQ, AMEX from 2000 to 2025. The strategy absorbs crashes at about half the rate of SPY (51.3% down capture) but trails on absolute return (6.57% vs 7.85% CAGR). Honest results from a 25-year run.
FCF growth
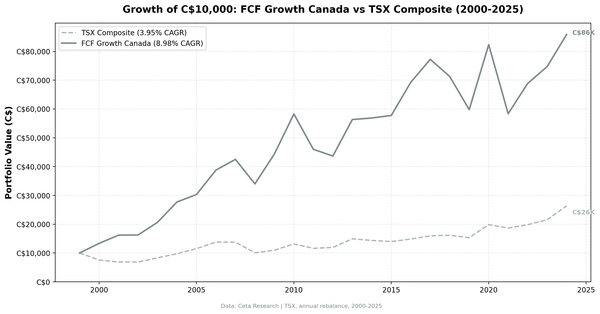
Canada FCF growth stocks produced 8.98% CAGR over 25 years, beating the TSX Composite by 5.03 percentage points per year. 21.2% down capture means the portfolio absorbed only a fifth of the TSX downside in down years.
FCF growth
We ran the same FCF growth screen across 13 exchanges over 25 years. Nine of 13 beat their local benchmark, but the real story is data coverage: once periods without usable prices are held in cash, the UK collapses from best market to barely positive.
FCF growth
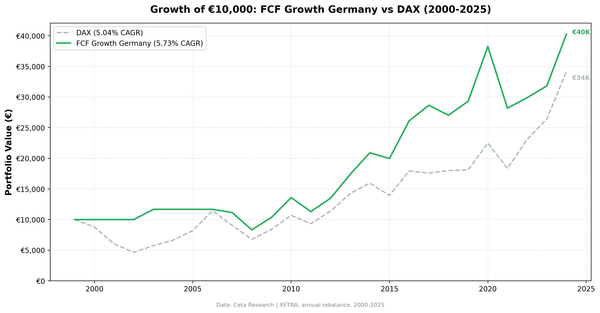
German FCF growth stocks beat the DAX by just 0.69 percentage points a year over 25 years, and a German-domicile test flips that negative. The durable result is risk: 42.9% down capture and a -28.62% worst drawdown against the index's -53.43%.
momentum investing
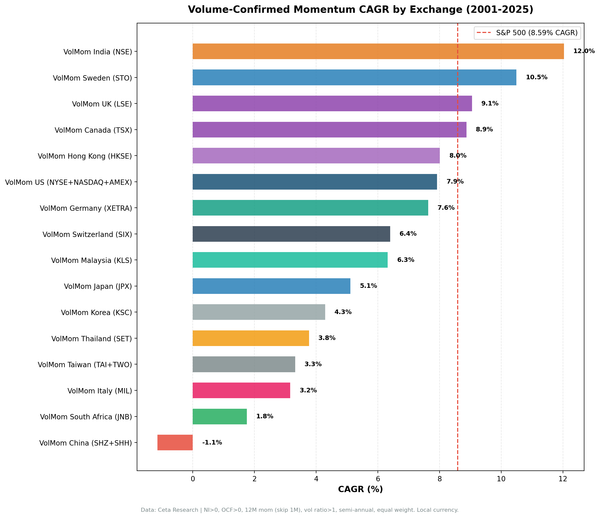
Same strategy, 17 global exchanges, 25 years. Volume-confirmed momentum returned +7.60% excess vs the FTSE 100 and +6.81% vs the OMX Stockholm 30, but -1.15% vs the Sensex in India and -0.67% vs the S&P 500 in the US. The local benchmark drives most of the ordering.
momentum investing
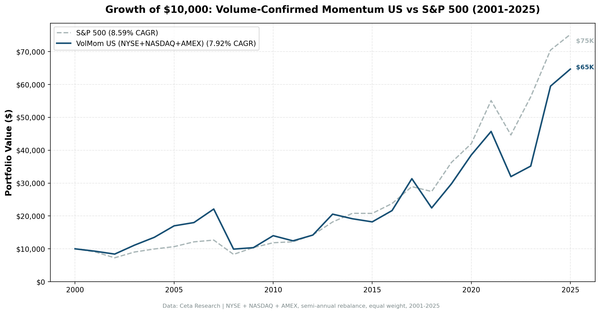
We added volume confirmation to 12-month momentum on US stocks: rising 3-month volume, positive earnings, positive cash flow. From 2001 to 2025 it returned 7.92% annually vs 8.59% for SPY, with 145.7% down capture. The paper cited for the idea found high-volume winners reverse faster.
earnings surprise
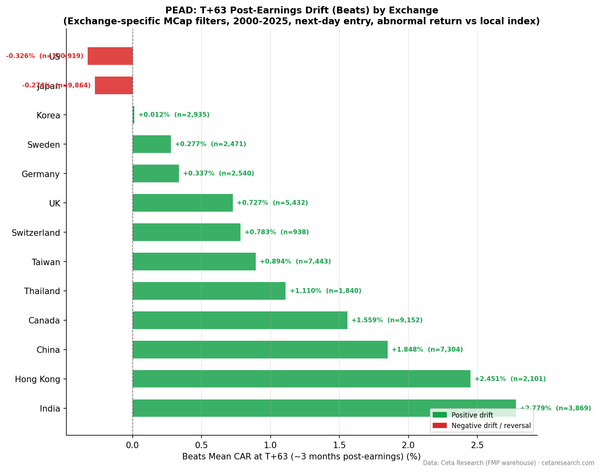
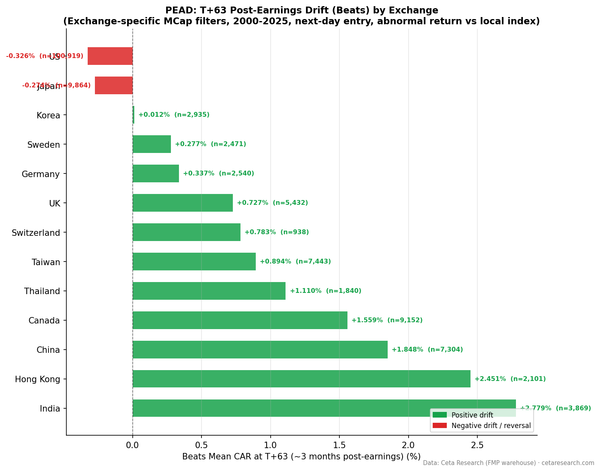
We tested Post-Earnings Announcement Drift on 13 global exchanges with 280,000+ events, 2000-2025, entering at the next day's close. The tradeable drift is far smaller than same-day studies show. Taiwan leads (+4.52% spread), India leads the beat side.
earnings surprise
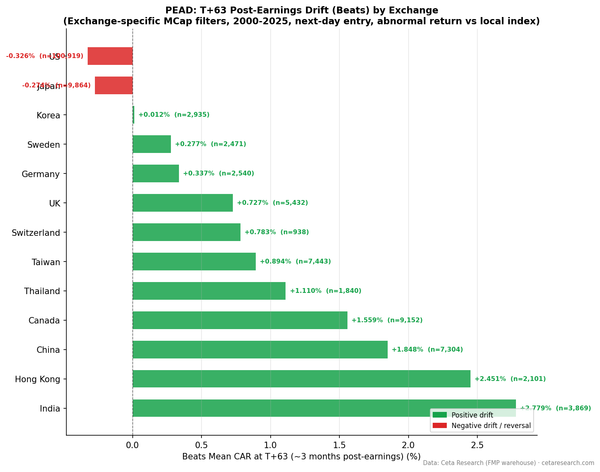
UK earnings drift is a beat-side signal vs the FTSE 100. Biggest beats produce +1.18% CAR at T+63, or +1.38% net of baseline. The miss side does almost nothing. Q5-Q1 spread: +1.59%.
earnings surprise
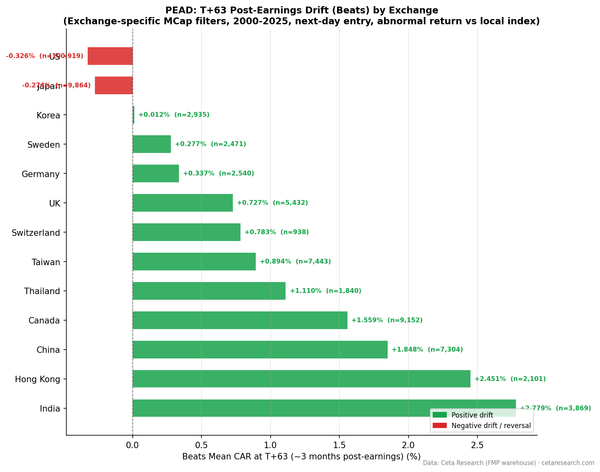
Thailand's earnings drift is a beat-side signal vs the local SET Index. Biggest beats +1.34% at T+63, or +1.50% net of baseline, and the miss side is weaker and not significant. Q5-Q1 spread: +2.22%.
earnings surprise
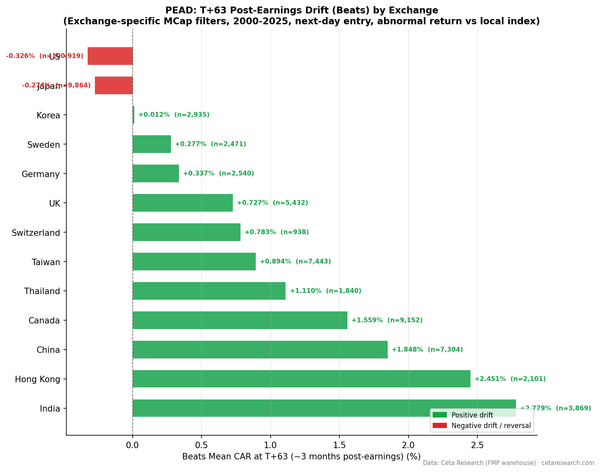
China has the lowest beat rate of any exchange we tested: 34.8%. But when Chinese companies beat, the drift survives a next-day entry: Q5 +2.58% at T+63, or +1.46% net of baseline. Q5-Q1 spread: +2.33%.
earnings surprise
Taiwan has the widest earnings-surprise spread in our study: +4.52% at T+63 vs the TAIEX, now the largest after the correction. Both sides survive. Worst misses -3.08% (-2.69% net), biggest beats +1.45%.